Valuing a Forward Contract on a Dividend-Paying Asset
- LevelCFA Level ISee similar
- TopicDerivativesSee similar
- SubtopicFORWARD MARKETS AND CONTRACTS
- DifficultyHardSeveral steps or a common exam trapSee similar
- Published
FIP-CFA-L1-DER-001
An investor entered a long position in a 9-month forward contract on an equity index three months ago. The original forward price established at initiation was $105. Currently, the spot price of the index is $110, and the present value of expected dividends over the remaining 6 months of the contract is $2. Assuming an annual risk-free rate of 4%, the current value of the long forward position is closest to:
Correct answer: A. $5.04
Formula
Why A is correct
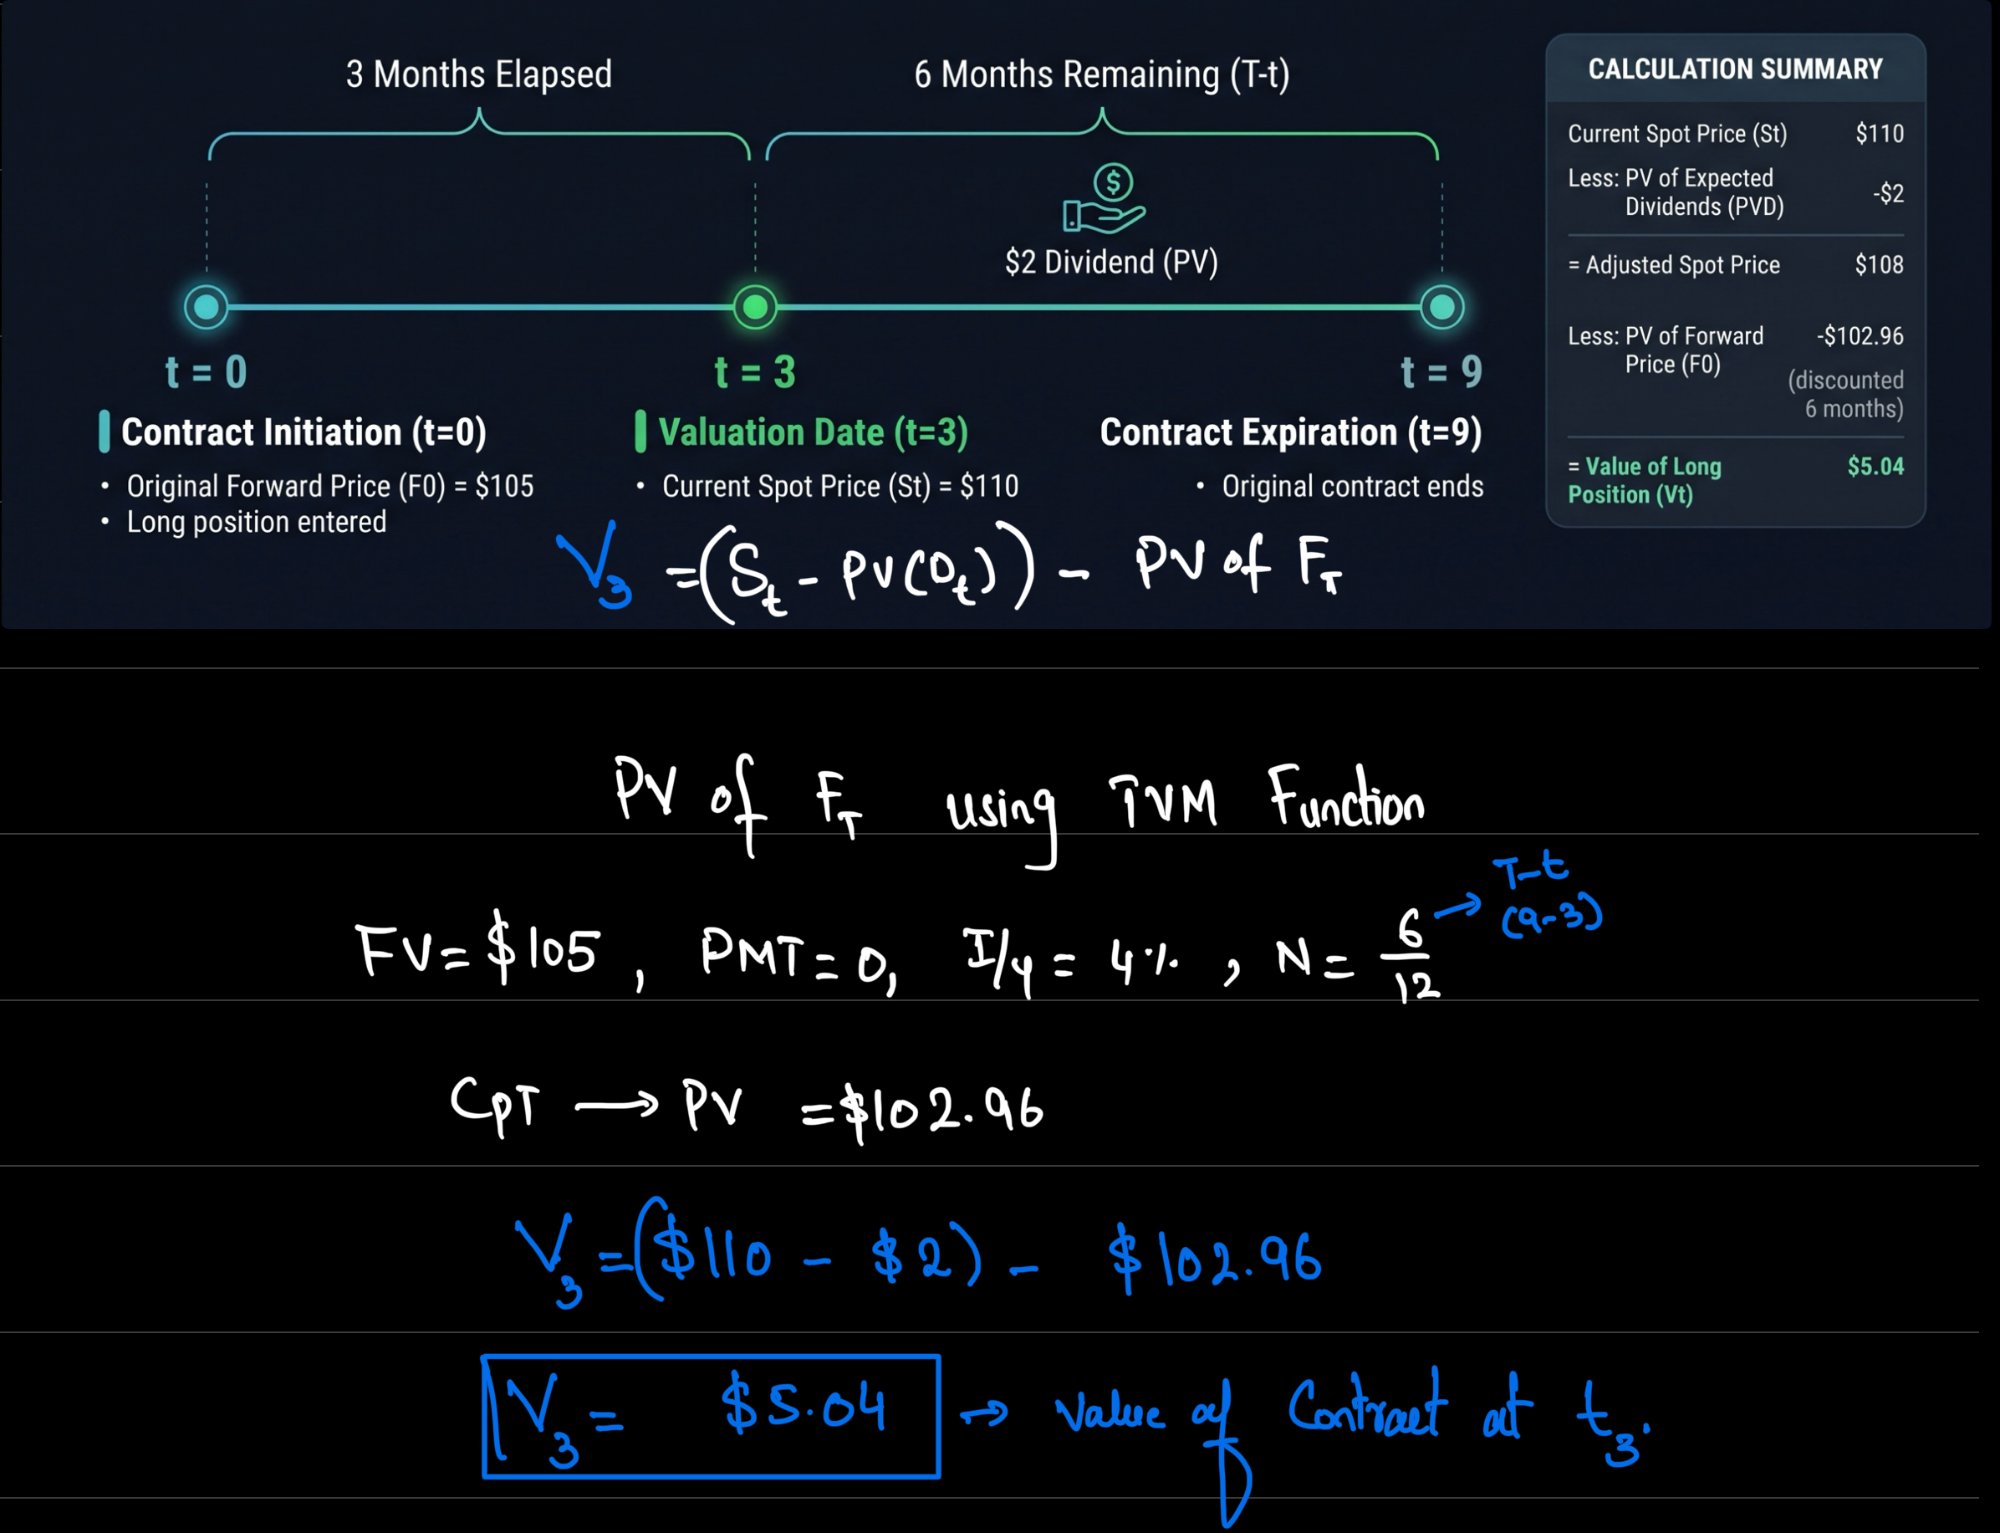
Step 1: Determine the current spot price adjusted for the present value of remaining dividends ().
Step 2: Calculate the present value of the original forward price using the time remaining to maturity (6 months, or 0.5 years).
.
Step 3: Subtract the present value of the forward price from the dividend-adjusted spot price.
.
Why B is incorrect
This calculation ignores the present value of the dividends ().
Why C is incorrect
This simply takes the current spot price minus the original forward price (),
Common exam trap
Most candidates confused Pricing with Valuing.
- Pricing finds the forward rate at initiation (when the value of the contract is zero).
- Valuing calculates the mark-to-market (MTM) worth during the contract's life.
- Candidates also frequently forget to use the remaining time to maturity () when discounting, mistakenly using the original contract term.
1-on-1 CFA® Level I coaching in Abu Dhabi or online across the UAE, AED 150 / hour
Challenge a friend
Get tomorrow’s question
MAWritten by Muhammad Ahmed RazaLead Instructor · CFA® & FRM®