One-Period Binomial Tree: Risk-Neutral Probabilities and Call Valuation
- LevelCFA Level ISee similar
- TopicDerivativesSee similar
- SubtopicOPTION VALUATION
- DifficultyHardSeveral steps or a common exam trapSee similar
- Published
FIP-CFA-L1-DER-002
A quantitative analyst is valuing a European call option on a non-dividend-paying stock using a one-period binomial model. The analyst has gathered the following market data:
| Description | Value |
|---|---|
| Current Stock Price (S0) | $50.00 |
| Option Strike Price (X) | $50.00 |
| Up-move factor (U) | 1.20 |
| Down-move factor (D) | 0.80 |
| Risk-free rate per period (r) | 4.0% |
Based on this data, the risk-neutral probability of an up move and the current price of the call option () are closest to:
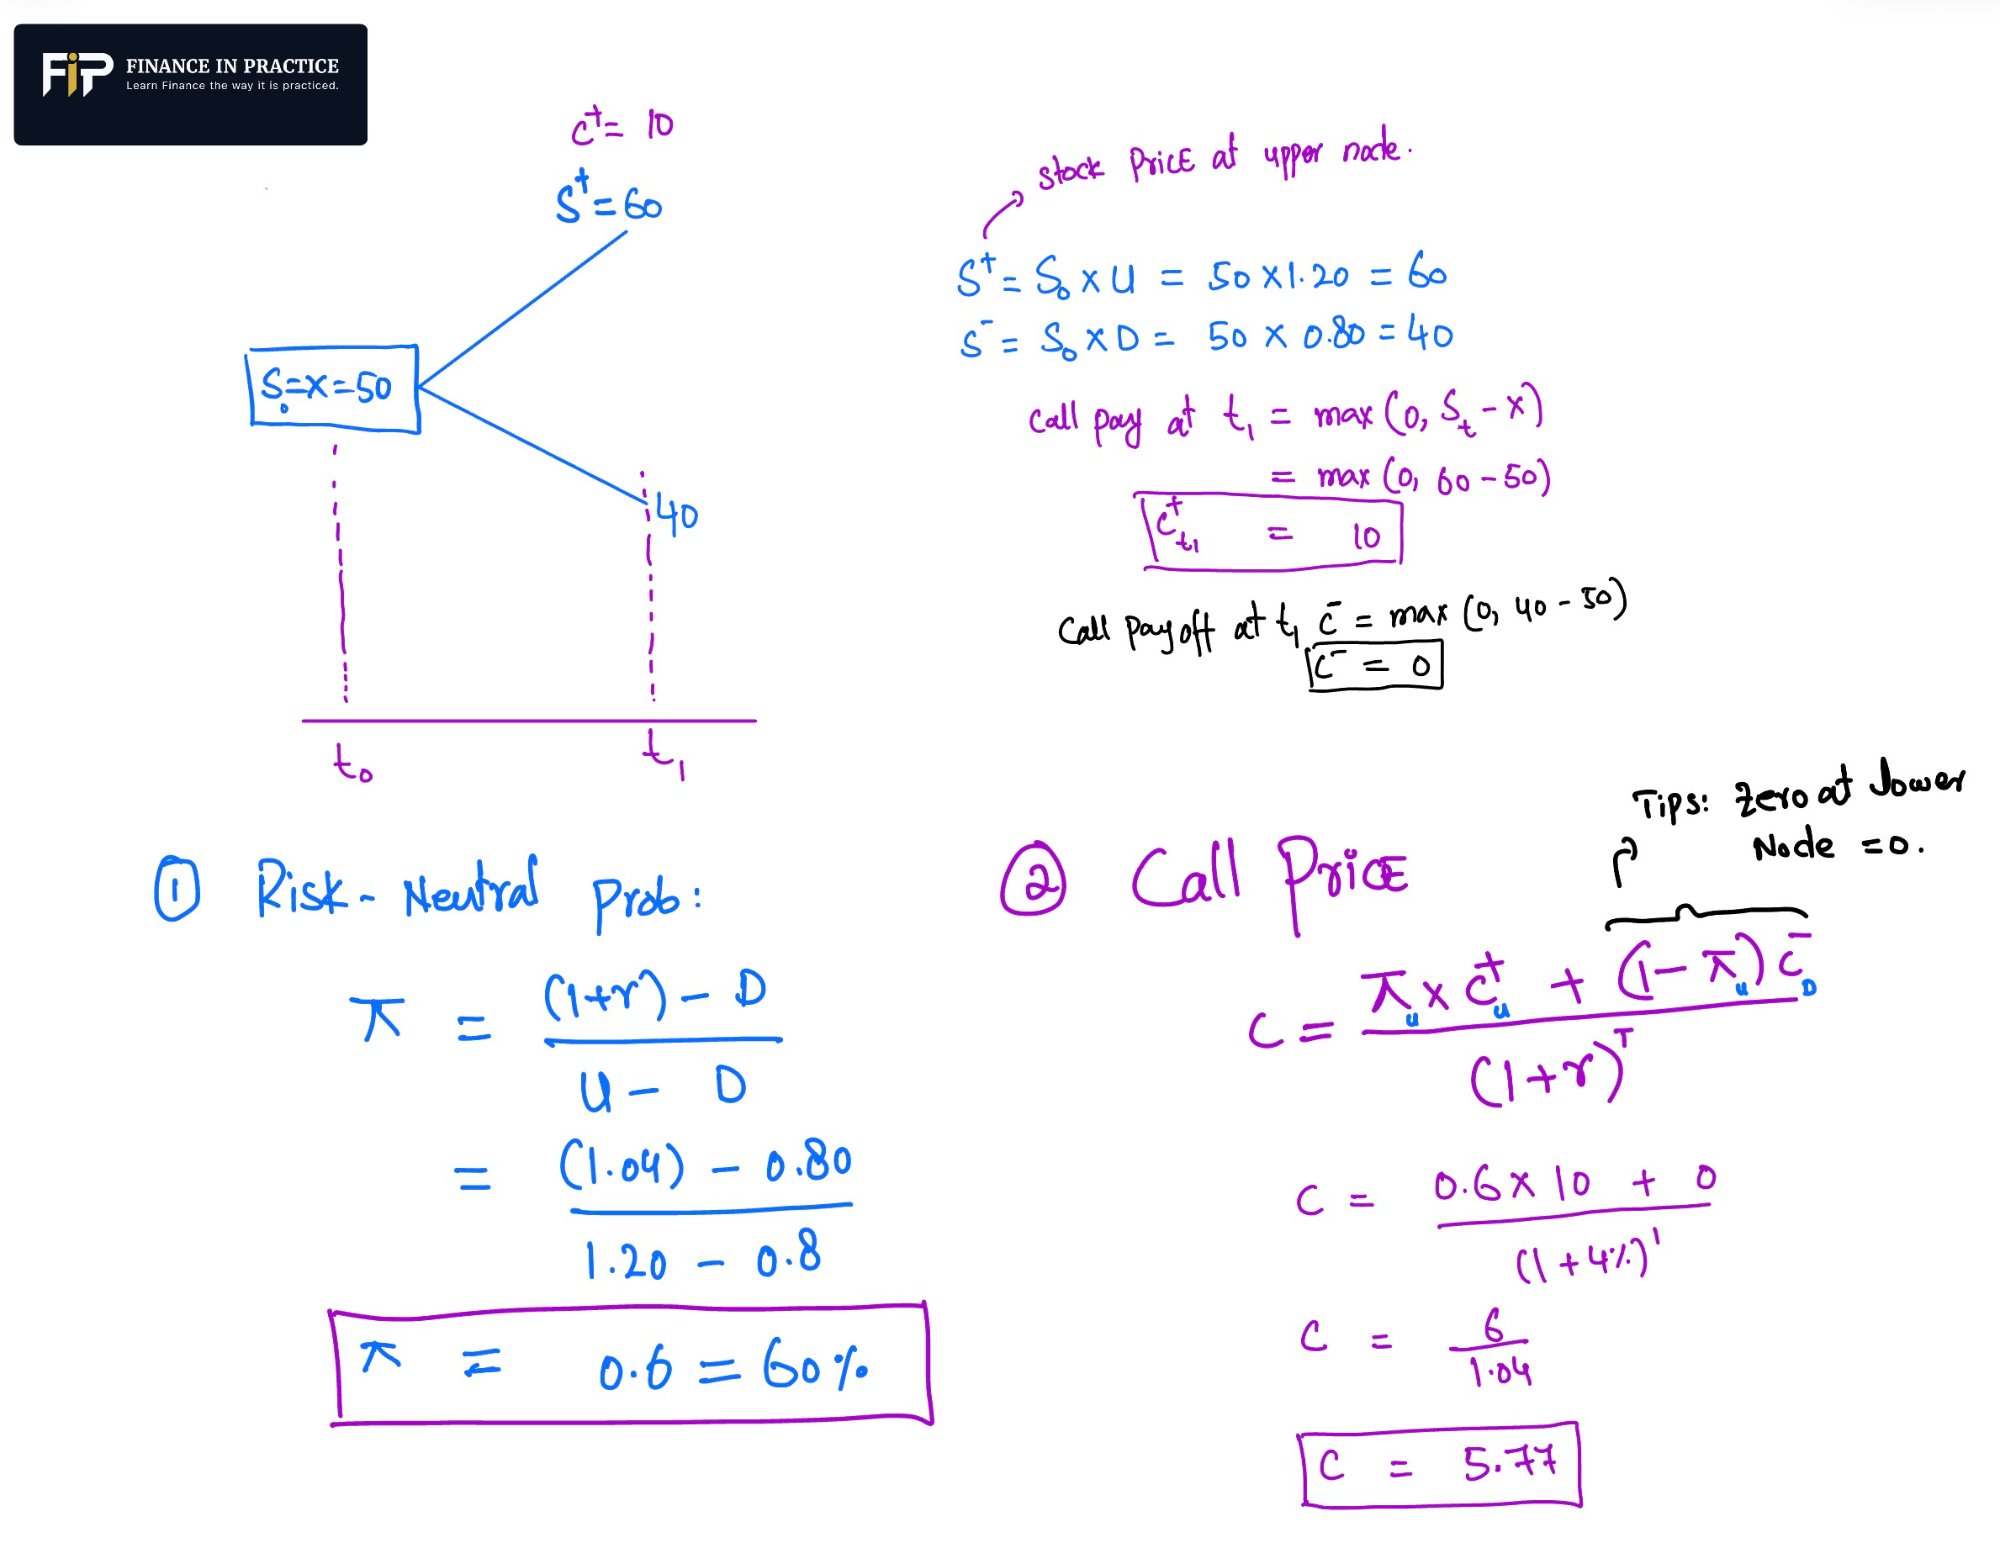
Correct answer: A. Risk-neutral probability: 60%; Call Price: $5.77
Formula
Why B is incorrect
Assumes a 50/50 "physical" probability (a coin flip) rather than calculating the risk-neutral probability.
Why C is incorrect
Forgets to discount the payoff back to present value using the risk-free rate.
Common exam trap
- Using 50% probability instead of solving for implied risk-neutral probability.
- In derivative pricing, investor/real-world probability of stock going up or down is completely irrelevant.
Practitioner insight
In the real world, for options volatility surfaces and derivative pricing engines, even used risk-neutral probability.
MAWritten by Muhammad Ahmed RazaLead Instructor · CFA® & FRM®
1-on-1 CFA® Level I coaching in Abu Dhabi or online across the UAE, AED 150 / hour
Challenge a friend
Get tomorrow’s question
Original practice question by Finance in Practice.